

Business Operation · 2025
In this section24 topics
- Corporate Information4 items
- Dividend Policy2 items
- Major Shareholders2 items
- Business Strategies Overview6 items
- Material Changes & Developments2 items
- Use of Proceeds from Securities Offerings3 items
- Commitments Made in the Registration Statement1 item
- Group Operating-Structure Policy1 item
- Companies Where the Company Holds ≥10%1 item
- Shareholders with Potential Conflict of Interest1 item
- Relationships Among Major Shareholders1 item
- Shareholders' Agreement1 item
- Shareholding Diagram (Group Structure)4 items
- Income Structure4 items
- Product / Service Characteristics2 items
- Research & Development6 items
- Assets Used in the Business6 items
- Marketing Policy & Competition3 items
- Procurement of Products & Services2 items
- Nature of Business — Overview1 item
- Product Information — Overview1 item
- Projects Under Construction1 item
- Debentures & Bills of Exchange1 item
- Convertible Securities1 item
Corporate Information
Company Name
TQR PUBLIC COMPANY LIMITED
Telephone
0-2150-8560
Website
https://www.tqr.co.th
ir@tqr.co.th
Dividend Policy
Dividend Policy
The Company has established a dividend policy aimed at maximizing benefits for both shareholders and the Company. The Company intends to pay dividends at a rate of not less than 50% of net profit after corporate income tax and after allocations to the statutory reserve and other reserves as required by law or as determined by the Company, based on the Company’s consolidated financial statements. However, the dividend payment may vary depending on factors such as net cash flow, financial position, operating results, investment plans for various projects, as well as other necessities and appropriateness in the future, as considered appropriate by the Board of Directors and/or the shareholders. Such considerations shall be made with due regard to the best interests of the shareholders.
The Board of Directors may propose the annual dividend payment of the Company, which must be approved by the Annual General Meeting of Shareholders, except for interim dividends. The Board of Directors has the authority to approve the payment of interim dividends from time to time when it considers that the Company has sufficient profits to do so, in order to maximize benefits to both shareholders and the Company. Any such interim dividend payment shall be reported to the shareholders at the next shareholders’ meeting.
Historical Dividend Payments
| This Year | Last Year | 2 Years Ago | 3 Years Ago | 4 Years Ago | Metric | Description |
|---|---|---|---|---|---|---|
| 0.44 | 0.44 | 0.44 | 0.43 | 0.44 | Net profit per share (Baht : Share) | Net profit per share (baht : share) |
| 0.4 | 0.4 | 0.4 | 0.39 | 0.32 | Dividend per share (Baht : Share) | Dividend per share (baht : share) |
| 0 | 0 | 0 | 0 | 0 | Dividend stock ratio (Number of original shares: dividend shares) | Ratio of stock dividend payment (existing share : stock dividend) |
| 0 | 0 | 0 | 0 | 0 | Dividend share value per share (Baht : Share) | Value of stock dividend per share (baht : share) |
| 0.4 | 0.4 | 0.4 | 0.39 | 0.32 | Total dividend payment value (Baht : Share) | Total dividend payment (baht : share) |
| 91.51 | 91.84 | 91.72 | 91.28 | 75.01 | Dividend payout ratio to net profit (%) | Dividend payout ratio compared to net profit (%) |
Business Strategies Overview
Introduction
The Company is firmly committed to conducting its business and generating sustainable growth through the full integration of Environmental, Social, and Governance ("ESG") dimensions into its operations, while giving due consideration to the impact on all stakeholder groups across the entire business value chain. In this regard, during 2025, the Board of Directors reviewed and approved the Company's vision, mission, and operational strategies, to ensure their continued alignment with the Company's business direction and the evolving internal and external context across both the short-term and long-term horizons.
Chairman's Message
The past year has once again reflected both the challenges and opportunities facing the insurance and reinsurance industry, amid heightened economic volatility, rapid technological transformation, and an increasingly complex array of emerging risk profiles. Within this context, TQR Public Company Limited has remained steadfast in conducting its business with prudence and diligence, drawing upon over 20 years of accumulated expertise and experience in the reinsurance industry.
The Company places paramount importance on the development of reinsurance products and solutions that genuinely address the evolving needs of its clients, while simultaneously strengthening its competitive capabilities through the adoption of technology and innovation, and the strategic expansion of investments in related businesses to support the Company's long-term growth, conducted within a framework that gives appropriate consideration to Environmental, Social, and Governance ("ESG") dimensions.
Furthermore, the Company places a strong emphasis on comprehensive risk management across all dimensions, the maintenance of high service delivery standards, and the cultivation of long-term relationships with direct insurance companies, reinsurance companies, and business partners both domestically and internationally, anchored in the principles of transparency, accountability, and Code of Conduct, which constitute the fundamental pillars that have earned the Company enduring trust and enabled the continuity of its business operations.
Looking ahead, the Company will continue to drive its organizational advancement under a sustainable growth strategy, fully integrating ESG principles into its strategic planning, operational execution, and human capital management, with the aim of creating long-term value for shareholders, clients, business partners, employees, and society at large, while aspiring to be a strong, trusted, and mutually thriving partner in the reinsurance industry.
On behalf of TQR Public Company Limited, I would like to extend my sincere gratitude to the Board of Directors, shareholders, clients, business partners, and all employees for their invaluable contributions and unwavering support in driving the Company's continued and steady progress. I trust that all stakeholders can be assured that the Company will remain firmly committed to advancing the organization on the foundation of responsibility and sustainability.
Vision
To be the leading provider of reinsurance placement and insurance product development, delivering comprehensive and fully integrated business development solutions.
Objectives
To build credibility and earn the trust of business partners by delivering tailored advisory services that effectively and efficiently address clients' reinsurance placement needs, with the aim of advancing the insurance business and fostering mutual sustainable growth.
Goals
To expand the Company's business by continuously growing its partner network, encompassing both cedant insurance companies and reinsurance companies.
To broaden the range of reinsurance treaty structures to accommodate innovative policy forms that are responsive to the increasingly complex and evolving risk landscape, both present and future.
To provide knowledge-sharing and advisory services to the Company's business partners and stakeholders, with the aim of fostering sustainable development across the insurance and reinsurance industry.
Business Strategies
The Company has formulated its business strategies with a focus on strengthening long-term competitive capabilities, while continuously elevating its service excellence, under the overarching goals of sustainable growth and value creation for all stakeholders across the business value chain. Emphasis is placed on holistic organizational development encompassing human capital, operational processes, technology, and financial performance.
1. Strengthening the Core Business and Competitive Differentiation
Given that the Company operates in the reinsurance brokerage business in competition with both domestic and international operators, a key strategic pillar is the pursuit of Differentiation from competitors through the development of an Advisory-driven Model, focusing on in-depth analytical capabilities and specialist advisory services, to generate added value for its principal business partners, namely cedant insurance companies, in the areas of innovative insurance product design and the structuring of appropriate reinsurance programmes for effective risk management.
The Company continuously exchanges and utilizes actuarial and insurance statistical data in collaboration with its business partners, and conducts analysis of both domestic and international data to develop insurance policies and solutions capable of responding to an increasingly complex and rapidly evolving market landscape.
2. Business Scope Expansion and Integrated Solutions
The Company seeks to expand its role from that of a reinsurance broker to a fully Integrated Reinsurance Solution Provider, encompassing risk management consulting, claims advisory services, and the development of insurance and reinsurance platforms, with the aim of enhancing service delivery efficiency and elevating the overall client experience.
3. Business Network Development and Strategic Investment
The Company places significant importance on fostering collaboration and leveraging synergies within its business group and among its strategic partners. Subsidiary and associate company play a pivotal role in supporting business opportunity expansion, new product and service development, and the deployment of specialist expertise to reinforce the core business. In addition, the Company focuses on efficient investment portfolio management to optimize returns and ensure long-term financial stability.
4. Organizational Development and ESG-driven Strategy
The Company's strategic execution is firmly grounded in the TQR Corporate Culture, underpinned by three core values: collaborative commitment and dedication (Team: T), delivery of quality work with care and diligence (Quality: Q), and the cultivation of business partner and stakeholder relationships with integrity and fairness (Relationship: R). This is complemented by continuous human capital development, the enhancement of operational processes through integration and automation, and the advancement of the organization under an ESG-driven framework, in support of stable and sustainable long-term growth.
The management has communicated the operational strategic plan to executives and employees at all levels to ensure a clear and consistent understanding and its tangible implementation, while regularly monitoring progress and performance against the established strategic objectives. Furthermore, the Company conducts periodic reviews and assessments of its strategic plan to ensure operational effectiveness and alignment with the evolving business context, and formally presents such plans to the Board of Directors for consideration on an annual basis.
Material Changes & Developments
Introduction
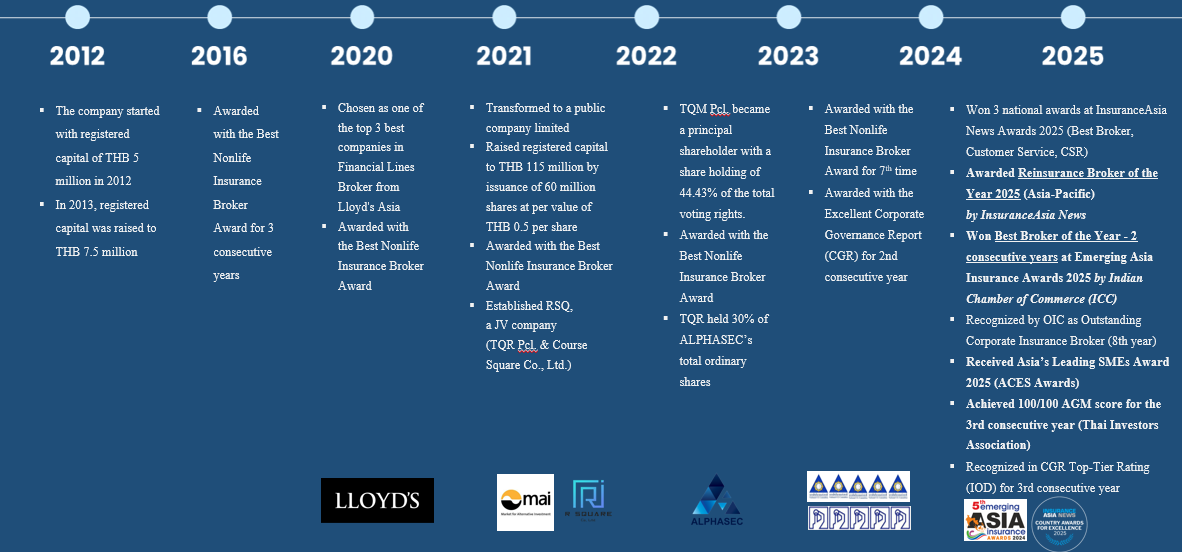
Material Changes & Developments
| Year | Description |
|---|---|
| 2,024 |
|
| 2,023 |
|
| 2,022 |
|
| 2,021 |
|
| 2,020 |
|
| 2,015 |
|
| 2,013 |
|
| 2,012 |
|
| 2,025 |
|
| 2,018 |
|
| 2,017 |
|
| 2,016 |
|
Use of Proceeds from Securities Offerings
Introduction
TQR Public Company Limited conducted its Initial Public Offering ("IPO") of 60,000,000 newly issued ordinary shares at an offering price of THB 5.10 per share, with a par value of THB 0.50 per share. The shares were offered to persons at the discretion of the underwriter, institutional investors, the Company's patrons, as well as directors, executive management, and employees of the Company. The Company received net proceeds from the capital increase, after deducting all costs and expenses relating to the offering, totalling THB 295.7 million.
Is There Money Raised from a Securities Offering Still to Report On?
Yes
Offerings
| Type of Securities | Amount Raised Given As | Amount Raised (Million Baht) | Uses of the Money | Used as Declared? | Progress / Reasons and Measures if Not Used as Declared |
|---|---|---|---|---|---|
| Equity Instruments | 2873 | 295.7 | 2027-12 · Objective: Investment in information technology system development to promote operational efficiency improvement platform · Period type: 2871 · Start period: 2027-12 · Spent amount type: 2873 · Start spent amount: 39.1 · Expected amount type: 2873 · Start expected amount range: 40.0 · 2027-12 · Objective: Reinsurance model development and analysis project · Period type: 2871 · Start period: 2027-12 · Spent amount type: 2873 · Start spent amount: 4.6 · Expected amount type: 2873 · Start expected amount range: 20.0 · 2027-12 · Objective: Investments in other related businesses · Period type: 2871 · Start period: 2027-12 · Spent amount type: 2873 · Start spent amount: 34.1 · Expected amount type: 2873 · Start expected amount range: 235.7 | Y |
|
Commitments Made in the Registration Statement
Are There Commitments or Conditions from an Offering or Listing?
No
Group Operating-Structure Policy
Description
In overseeing the operations of subsidiary and associated company, the Board of Directors will consider sending the Company's representatives who have the qualifications and experience appropriate to the businesses in which the Company invests to serve as directors of such subsidiary and associated company. Such representatives may be the Chairman of the Board, Chief Executive Officer, director, senior executive, or any person of the Company who has no conflict of interest with the businesses of such subsidiary and associated company. This is to enable the Company to control and oversee the business and operations of subsidiary and associated company as if they were a unit of the Company. The Company therefore requires that the Company's representatives must manage the business of subsidiary and associated company in the best interests of the Company and ensure compliance with the laws relating to the business operations of such subsidiaries and/or associated companies. In addition, the sending of representatives to serve as directors of such subsidiary and associated company shall be in accordance with the Company's shareholding proportion.
The Company will closely monitor the financial status and operating results of its subsidiary and associated company, including directing them to maintain information and accounting records for the Company's review.
Companies Where the Company Holds ≥10%
Companies (≥10% Holding)
| Company Name | Address | Province | Zip Code | Telephone | Business Type | Security Type | Shares | Paid-up Shares |
|---|---|---|---|---|---|---|---|---|
| R SQUARE COMPANY LIMITED | No. 46/7 Rungrojthanakul Building 8th Floor, Ratchadapisek Road, Huai Khwang Sub-district, Huai Khwang District | Bangkok | 10310 | (+66)-2150-8577 | Providing online learning and training services, along with developing new technology that can identify users through facial recognition technology "Face Detection and Face Recognition" | Common shares | 30,000 | 30,000 |
| ALPHASEC COMPANY LIMITED | No. 57 Park Ventures Ecoplex 18th Floor, Witthayu Road, Lumphini Sub-district, Pathum Wan District | Bangkok | 10330 | (+66)-2309-3559 | Providing services and consulting in information technology, particularly in the areas of Cyber Security and Personal Data Protection (PDPA), including organizing relevant training programs and offering IT system auditing services | Common shares | 176,741 | 176,741 |
| R SQUARE COMPANY LIMITED | No. 46/7 Rungrojthanakul Building 8th Floor, Ratchadapisek Road, Huai Khwang Sub-district, Huai Khwang District | Bangkok | 10310 | (+66)-2150-8577 | Providing online learning and training services, along with developing new technology that can identify users through facial recognition technology "Face Detection and Face Recognition" | Common shares | 30,000 | 30,000 |
| ALPHASEC COMPANY LIMITED | No. 57 Park Ventures Ecoplex 18th Floor, Witthayu Road, Lumphini Sub-district, Pathum Wan District | Bangkok | 10330 | (+66)-2309-3559 | Providing services and consulting in information technology, particularly in the areas of Cyber Security and Personal Data Protection (PDPA), including organizing relevant training programs and offering IT system auditing services | Common shares | 176,741 | 176,741 |
Income Structure
Introduction
The Company's primary revenue comes from providing reinsurance services. The Company receives remuneration in the form of reinsurance brokerage fees from the reinsurer, accounting for approximately 95.85% of the Company's total revenue in 2024. Other income consists of interest income, dividend income, gains on disposal of assets, and unrealized gains on investment securities.
Revenue recognition from reinsurance brokerage services can be categorized based on the reinsurance contract method, divided into 2 types:
1. Treaty Reinsurance
The Company recognizes revenue from treaty reinsurance services when it receives a notification from the cedant according to the terms agreed upon in the reinsurance treaty. The cedant will prepare a Statement of Account (SOA) after the account closing, according to the agreed-upon period, such as quarterly or monthly. As the amount of such revenue is beyond the Company's control and cannot be reliably estimated, the Company will not recognize revenue until the reinsurance premium information is reasonably certain.
2. Facultative Reinsurance
The Company recognizes revenue from facultative reinsurance services when the policy is effective, the reinsurance arrangement is complete, or confirmation is received.
Product / Service Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue from operations | Total revenue from operations | 278,989.87 | 100 | 258,917.16 | 100 | 249,931.47 | 100 |
| Traditional Business | 86,285.23 | 30.93 | 74,561.99 | 28.8 | 67,767.02 | 27.11 | |
| Alternative Business | 179,496.36 | 64.34 | 172,173.06 | 66.5 | 170,221.98 | 68.11 | |
| Other Businesses | 1,635.56 | 0.59 | 1,162.82 | 0.45 | 2,607.84 | 1.04 | |
| Other | Others | 11,572.72 | 4.15 | 11,019.29 | 4.26 | 9,334.63 | 3.73 |
Export Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue | Total revenue | 278,989.87 | 100 | 258,917.16 | 100 | 249,931.47 | 100 |
| Domestic | Domestic | 278,989.87 | 100 | 258,917.16 | 100 | 249,931.47 | 100 |
| International | International | 0 | 0 | 0 | 0 | 0 | 0 |
Other Income
| Operating Other Income | Non-Operating Other Income | Share of Profit |
|---|---|---|
| 1710 · As of year: 11572.72 · Description: Total other income · As of yesteryear: 11019.29 · As of year before yesteryear: 9334.63 · 1711 · As of year: 0.0 · Description: Other income from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1712 · As of year: 11572.72 · Description: Other income not from operations · As of yesteryear: 11019.29 · As of year before yesteryear: 9334.63 | 1713 · As of year: 2525.97 · Description: Share of profit · As of yesteryear: 2966.0 · As of year before yesteryear: 684.0 |
Product / Service Characteristics
Business Type
3115
Business Groups
| Business Group | Description |
|---|---|
| Insurance Brokerage | The Company operates as a Reinsurance Broker under the regulatory supervision of the Office of Insurance Commission ("OIC"). The Company's business operations are currently categorized into two business segments: (1) Traditional Business and (2) Alternative Business. Within each business segment, direct insurance companies may elect to arrange reinsurance through either of the following two (2) methods: (1) Treaty Reinsurance and (2) Facultative Reinsurance.
1. Traditional Business The Company acts as an intermediary between direct insurance companies and reinsurance companies, providing reinsurance placement services encompassing both Treaty Reinsurance and Facultative Reinsurance across all classes of business, including, amongst others, motor insurance reinsurance treaties, property insurance reinsurance treaties, and miscellaneous insurance reinsurance treaties. In this segment, direct insurance companies independently develop, market, and distribute their own insurance products and seek to distribute their risk exposures to reinsurers. They accordingly engage the Company to source, coordinate, negotiate, and facilitate reinsurance arrangements between direct insurance companies and reinsurers, with the objective of achieving full and effective execution of reinsurance contracts. The Traditional Business currently constitutes the Company's principal business segment. 2. Alternative Business The Company serves as an intermediary between direct insurance companies and reinsurance companies in the placement of both Treaty Reinsurance and Facultative Reinsurance, in a manner consistent with the Traditional Business described above. Under the Alternative Business segment, the Company adopts a proactive business approach by actively seeking opportunities to participate in the collaborative analysis and development of insurance products with its business partners, providing advisory services on innovative insurance products sourced from international markets, and adapting such products to align with the Thai insurance market, while coordinating between its business partners to facilitate the efficient execution of reinsurance contracts. Examples of products within this segment include personal accident and travel accident reinsurance treaties, health insurance reinsurance treaties, and specialty insurance reinsurance treaties. The Company anticipates that the revenue contribution from the Alternative Business segment will grow in line with the expanding opportunities presented by emerging insurance product innovations in the future. Reinsurance Arrangements can be separated into two methods as follows: 1. Treaty Reinsurance Treaty Reinsurance is a reinsurance arrangement structured under pre-agreed terms and conditions between a direct insurance company and a reinsurer, whereby the reinsurer agrees to accept reinsurance in accordance with the broadly defined parameters specified in the reinsurance treaty, such as policy type, coverage scope, and sum insured. Where a policy satisfies the pre-agreed conditions, the reinsurer automatically accepts reinsurance for all such qualifying policies. The key advantages of Treaty Reinsurance are as follows:
2. Facultative Reinsurance Facultative Reinsurance is a reinsurance arrangement between a direct insurance company and a reinsurer, under which both parties retain the discretion to negotiate reinsurance premium rates on a case-by-case basis. This method is particularly suited to specialised or atypical risks falling outside the scope of standard treaty reinsurance arrangements, or to large-scale risks that exceed treaty parameters. The key advantages of Facultative Reinsurance are as follows:
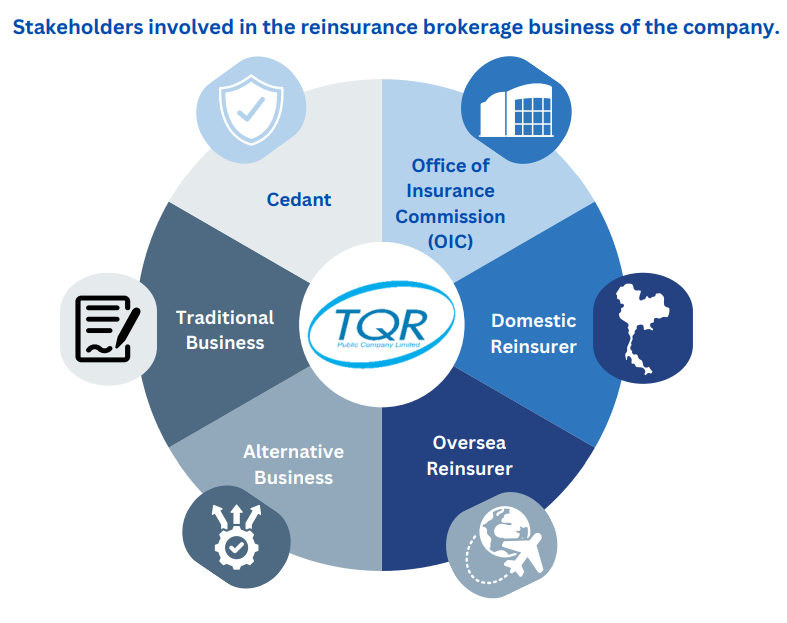
In respect of both types of reinsurance arrangements, Treaty Reinsurance and Facultative Reinsurance, the Company acts as an intermediary in the placement of reinsurance between direct insurance companies and reinsurers, providing advisory services, recommending appropriate terms and conditions, and conducting negotiations in its capacity as a reinsurance broker on behalf of direct insurance companies, in order to coordinate and facilitate the structuring and execution of reinsurance contracts across all classes of insurance business. The Company provides reinsurance brokerage services across a broad spectrum of insurance classes, covering the full scope of the insurance industry. Examples of reinsurance contracts for which the Company provides brokerage services are as follows:
|
Research & Development
Has R&D Policy (Y/N)
Yes
R&D Cost — Description
The Company does not engage in research and development activities in the form of technological or laboratory-based research. Expenses related to the development of knowledge, work processes, information systems, or personnel development are therefore included in administrative expenses or other operating expenses, and are not presented separately as research and development (R&D) expenses.
R&D Cost — Label
Research and development (R&D) expenses over the past 3 years (Million Baht)
R&D Cost — This Year
0.0
R&D Cost — Last Year
0.0
R&D Cost — 2 Years Ago
0.0
Assets Used in the Business
Permanent Assets — Description
As of December 31, 2025, the Company's main fixed assets used in its business operations consist of premises and equipment, as well as right-of-use assets. The net book value of these assets, as reflected in the audited financial statements, totals 9.37 million baht.
Permanent Assets — Appraisal
| Asset | Ownership | Obligation | Appraisal Value | Description |
|---|---|---|---|---|
| Building Renovation | Ownership | None | 457,010.68 | The property is located on the 8th floor of Rungrojthanakul Building, 46/7 Ratchadaphisek Road, Huai Khwang Subdistrict, Huai Khwang District, Bangkok. |
| Office Supplies and Equipment | Ownership | None | 888,888.59 | The property is located on the 8th floor of Rungrojthanakul Building, 46/7 Ratchadaphisek Road, Huai Khwang Subdistrict, Huai Khwang District, Bangkok. |
| Computer Equipment | Ownership | None | 1,529,381.61 | The property is located on the 8th floor of RRungrojthanakul BuildingRungrojthanakul Building, 46/7 Ratchadaphisek Road, Huai Khwang Subdistrict, Huai Khwang District, Bangkok. |
| Office Space | Not an owner | Assets under lease | 3,267,756.43 | Currently under a lease agreement for office space on the 8th floor of the Rungrojthanakul Building. The lease term is for three years from July 16, 2024 to July 15, 2027. |
| Vehicle | Not an owner | Assets under lease | 3,228,436.73 | 3 leased vehicles |
Intangible Assets — Description
The Company has intangible assets, including computer program such as accounting software, document management software, and human resource management software. As of December 31, 2025, the Company's intangible assets had a net book value after amortization of 21.83 million baht, as shown in the financial statements.
Intangible Assets — Appraisal
| Asset | Type | Appraisal Value | Description |
|---|---|---|---|
| Computer Program | Software | 21,834,681.22 | Such as accounting software, document management software, and human resource management software |
Has Subsidiaries Investment Policy (Y/N)
Yes
Subsidiaries Investment Policy — Description
The Company has an investment policy in subsidiaries and associated companies, focusing on investing in businesses that are related, complementary, or beneficial to the Company's operations, in order to enhance the Company's stability and performance. In making investment decisions and carrying out investments, the Company will adhere to its investment policy as well as that of its subsidiaries.
Marketing Policy & Competition
Reporting Mode
3117
Marketing Policy (Overall)
Competitive Strategy
The Company has formulated its competitive strategies and business conduct policies with the aim of strengthening long-term competitive capabilities and continuously elevating its service excellence, including the development of various technology platforms, underpinned by its core operating values of teamwork and collaboration (Team: T), quality delivery (Quality: Q), and the cultivation of relationships with all business stakeholders with integrity and fairness (Relationship: R).
Given that the Company operates in the reinsurance brokerage sector in competition with both domestic and international reinsurance brokers, its key strategic pillar is the pursuit of Differentiation from competitors, with a primary emphasis on the development of analytical capabilities and specialist advisory services, as these constitute the foundation of Value Creation for the Company's business partners. For cedant insurance companies, this translates into expanded opportunities to develop and launch innovative insurance products, while simultaneously securing appropriate reinsurance arrangements to mitigate the risk exposures inherent in such new product offerings. The Company also places paramount importance on cybersecurity and data information systems security, as well as the protection of client and consumer interests. To this end, the Company continuously coordinates the exchange and utilisation of insurance statistical data between its internal divisions and business partners, and conducts analysis of both domestic and international statistical data to develop new classes of insurance policies that are responsive to an increasingly complex and rapidly evolving market landscape. These efforts are directed towards safeguarding the data of clients, business partners, and stakeholders, mitigating cyber threat exposures, and continuously reinforcing confidence in the Company's services.
Competitive Advantages
The Company is recognized as one of the leading reinsurance brokerage operators in Thailand, supported by an executive management team and personnel with extensive knowledge and long-standing experience in the insurance industry, and over 20 years of specialist expertise in the reinsurance business. The strong relationships cultivated by the Company's management with its clients, comprising both cedant insurance companies and reinsurers, both domestically and internationally, are a testament to the Company's sustained competitive capabilities and the enduring trust it has earned from its business partners. Given that the Company operates in the reinsurance brokerage sector in competition with both domestic and international reinsurance brokers, its key strategic pillar is the pursuit of Differentiation from competitors, with a primary focus on analysis and development to promote the creation of innovative reinsurance products, with due regard to safety, health, and the impact on policyholders. This approach generates Value Added for business partners by building upon existing foundations to create new business opportunities for the Company in the future. Concurrently, the Company has embraced a forward-looking approach to the adoption and application of new innovations within its operations, with the aim of further enhancing the efficiency and quality of its service delivery.
Through the strategies and business management acumen of its experienced executive management, combined with the knowledge and capabilities of its personnel, the Company has consistently earned the trust of cedant insurance companies in sourcing reinsurance arrangements that effectively and continuously meet their requirements. The Company is further well-positioned to support direct insurance companies in the development of innovative insurance products tailored to their distribution channels and suited to the needs of Thai policyholders, thereby advancing the development of a fully integrated reinsurance brokerage business.
Service Channels
The Company provides services to its clients, comprising cedant insurance companies, encompassing advisory services, coordination, negotiation of the most appropriate terms and conditions, collaborative insurance product development, and the sourcing of reinsurance arrangements that precisely meet each cedant's requirements. In the placement of reinsurance contracts, the Company operates through its client-facing business personnel, whose responsibilities are segregated according to contract type, namely Treaty Reinsurance and Facultative Reinsurance. The Company's personnel apply their knowledge, competencies, and specialist expertise to source reinsurance arrangements that are optimally aligned with the individual requirements of each cedant. In addition, the Company continuously monitors industry news and insurance market developments in order to proactively present innovative reinsurance structures to both direct insurance companies and reinsurers for their ongoing consideration.
The Company incurs sales promotion expenses payable to external business referrers, in accordance with the Company's approved expenditure framework. However, the Company does not, maintain any policy of paying referral fees to its directors, executive management, or employees in respect of business referrals made to the Company.
Target Customer Groups
As described above, given that the Company operates as an intermediary in the placement of reinsurance contracts, its business partners comprise (1) Cedants and (2) Reinsurers, the details of which are as follows:
Cedant is a company licensed to conduct insurance business by the Office of Insurance Commission ("OIC"), the regulatory authority overseeing the insurance industry in Thailand.
Reinsurer is a company licensed to conduct reinsurance business under the regulatory authority of the jurisdiction in which the reinsurer is incorporated and registered.
Pricing Policy
The determination of reinsurance premiums is subject to negotiation between the direct insurance company and the reinsurer on a per-contract basis, taking into consideration factors such as the class of policy, the loss history of the insured assets, and the applicable terms and conditions of coverage, amongst others. The Company derives its revenue from reinsurance brokerage services, whereby the Reinsurance Brokerage Rate is determined by the scope of services rendered, the quality of business relationships, and the outcome of commercial negotiations. The Company maintains a policy of applying reinsurance brokerage rates that are competitive within the reinsurance brokerage industry. Such brokerage rates are not subject to regulatory control by the OIC.
Industry & Competition (Overall)
Industry Conditions
According to data published by the Thai General Insurance Association as of February 2026, there are currently 48 licensed non-life insurance companies authorised to conduct non-life insurance business in Thailand, comprising 47 direct non-life insurance companies and 1 reinsurance company.
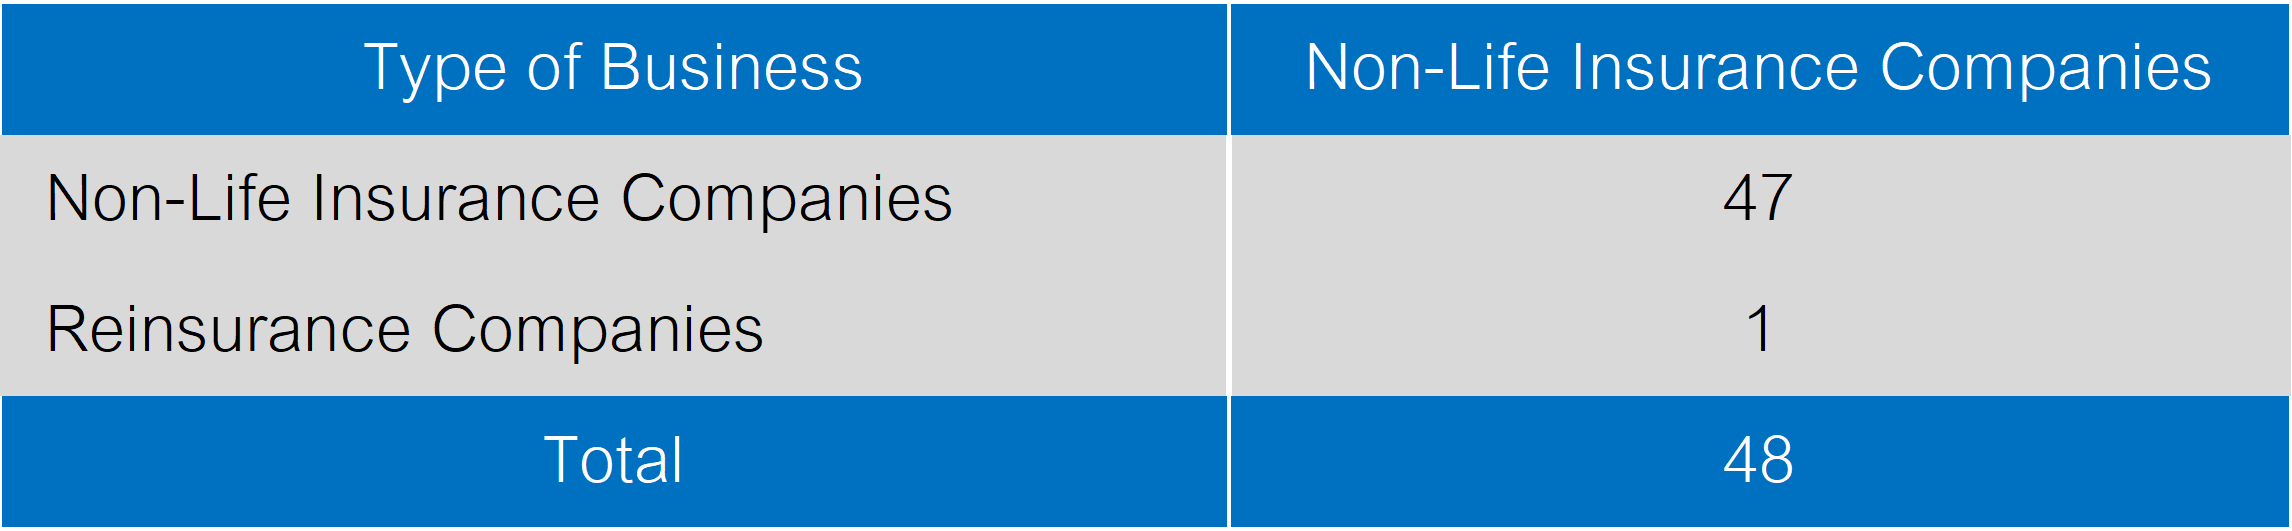
Source: Thai General Insurance Association
Given that the Company's core business is the provision of intermediary services in the placement of reinsurance for non-life insurance companies, the Company's growth trajectory is intrinsically aligned with the expansion of the Thai non-life insurance industry. The domestic non-life insurance sector has demonstrated continuous and sustained growth, driven by the overall economic development of the country, as well as increasing public awareness and understanding of the benefits of insurance as a mechanism for risk mitigation and the safeguarding of lives and assets. Importantly, insurance serves as an indispensable instrument for the conduct of business and industrial activities, thereby contributing to the stable and sustainable growth of the national economy.
Number of Non-life Insurance Policies and Premiums
During the period from 2021 to 2025, the total number of insurance policies nationwide changed in line with economic conditions and shifts in public demand for insurance coverage. In 2021, the number of policies stood at 73.28 million before declining significantly to 61.69 million in 2022, reflecting a slowdown in the market during that period.
However, from 2023 onward, the number of policies began to recover steadily, reaching 63.56 million in 2023, increasing to 66.40 million in 2024, and continuing to expand to 70.35 million in 2025, a level close to that observed prior to the slowdown.
This trend reflects a recovery in demand for insurance within the economy, as well as the role of the insurance industry as a risk management tool for both households and businesses. The increase in the number of policies in the latter period indicates an expansion of the insured customer base and greater stability of the Thai insurance market in the medium term, despite ongoing volatility in certain economic factors.
During the period from 2021 to 2025, Thailand’s insurance industry exhibited an overall positive growth trend. Total nationwide written premiums increased from THB 265,846 million in 2021 to THB 279,709 million in 2022, and continued to expand to THB 288,729 million in 2023, reflecting a recovery in economic activity and rising demand for risk management.
Although total written premiums declined slightly to THB 286,455 million in 2024, the decrease remained limited in magnitude. In 2025, total written premiums rebounded to THB 293,118 million, the highest level during the period under review. This performance underscores the stability of the insurance industry and its ability to adapt to a volatile economic environment.
Overall, these trends highlight the medium-term growth potential of the insurance business and reaffirm its important role in supporting the country’s overall economic system.
Proportion of Non-Life Insurance Premiums by Business Type
In 2025, the structure of total non-life insurance premiums in Thailand showed a clear distribution across major business lines. Voluntary motor insurance accounted for the largest share at 49% (THB 143,243.9 million), highlighting the continued importance of motor insurance within the Thai non-life insurance market and the sustained preference of policyholders for coverage in this segment.
This was followed by miscellaneous insurance at 20% (THB 57,980.5 million) and accident and health insurance at 18% (THB 53,358.9 million). Both segments continue to play a significant role in driving industry growth, particularly the health segment, which has been supported by increased health awareness and rising medical expenses.
Compulsory motor insurance (CTPL) accounted for 7% (THB 20,662.3 million), followed by fire insurance at 4% (THB 11,404.9 million) and marine and transport insurance at 2% (THB 6,467.5 million). These figures reflect a relatively stable structural composition of the market, aligned with demand from the logistics, real estate, and infrastructure sectors.
Overall, this premium structure illustrates the continuity of demand patterns in Thailand’s non-life insurance market in 2025, with motor insurance and miscellaneous insurance remaining the key drivers of the industry.
Total Reinsurance Premiums of Non-Life Insurance Business
According to the OIC data, reinsurance premiums for the non-life insurance business increased from 67,925 million baht in 2019 to 88,333 million baht in 2023 (the latest available data), or an average annual growth rate of 5.4% (CAGR). In 2023, reinsurance premiums accounted for 31.0% of total direct written premiums. Reinsurance is considered a crucial risk management tool for non-life insurance companies as it effectively spreads risk, enabling them to increase their underwriting capacity. It also enhances the stability of underwriting results, leading to financial stability. Therefore, reinsurance is a factor that drives the stable and sustainable growth of the non-life insurance industry.
Competitor
The reinsurance brokerage industry in Thailand is characterized by a relatively small number of market participants. According to data from the Office of Insurance Commission (OIC), there are a total of 14 companies registered as reinsurance brokers (source: Asia Insurance Review). Most of these entities are foreign-owned companies that have entered the Thai market to operate in this segment, such as Aon Thailand Co., Ltd. and Lockton Wattana Insurance Brokers (Thailand) Ltd., and etc.
Procurement of Products & Services
Reporting Mode
3117
Procurement (Overall)
Product Sourcing (Reinsurance Contract)
(1) Selection and sourcing of insurance companies (Cedant) and reinsurance companies (Reinsurer)
The Company has guidelines for selecting and sourcing clients or insurance companies (Cedant) and reinsurance companies (Reinsurer) as follows:
For insurance companies, they must be juristic persons approved to operate insurance businesses by the OIC. They must have a stable financial status and maintain a capital adequacy ratio according to the OIC's standards.
For the consideration and selection of reinsurers, they must be juristic persons approved to operate reinsurance businesses by the OIC or regulatory authorities and/or authorized persons under the country in which such company is registered. In addition, the Company has set additional qualifications and standards to be used in considering reinsurance offerings. The Company will consider the credit risk of reinsurance, which is referenced from the Risk-Based Capital Framework document by the OIC, with the following details:
- Foreign Reinsurers: The Company will consider the risk value from the credit rating of the reinsurer using information from Rating Agencies such as S&P, AM Best, Fitch, etc.
- Domestic Reinsurers: The Company will consider the risk value from the Capital Adequacy Ratio (CAR Ratio) of that reinsurer.
(2) Reinsurance Services
The Company has guidelines for providing reinsurance contract procurement services for the traditional reinsurance brokerage business (Traditional Business), which can be summarized as follows:
Analyze the data required for reinsurance by considering statistical data, risk characteristics, and other relevant details of each type of insurance product.
Advise, recommend, and present appropriate reinsurance terms to the insurance company (Cedant).
Negotiate with the reinsurer as a reinsurance broker for the insurance company (Cedant).
In terms of services for the group of reinsurance brokers with alternative channels and product development, the Company has additional service guidelines from the traditional reinsurance brokerage business (Traditional Business) as follows:
Collect statistical data on insurance and reinsurance, including relevant information and statistics such as economic data, market trends, consumer behavior, to analyze business trends related to insurance, including insurance products that meet the needs of the reinsurance market.
Look for opportunities and develop the above products jointly with insurance companies to suit the channels and target groups of each insurance company. There is a plan to develop customer satisfaction. If customers are not satisfied, the Company will have to adjust and set quantitative goals in developing customer satisfaction. There will always be an assessment of customer satisfaction after receiving the service.
Coordination and Control of Service Providing (Reinsurance Contract)
The Company will act as an intermediary in coordinating between the insurance company and the reinsurance company in arranging reinsurance. The steps are as follows:
1. Offer
When an insurance company wishes to use the Company as a reinsurance broker to procure a reinsurance contract, the Company will act as an intermediary in submitting an offer or proposal for reinsurance from the insurance company to the reinsurer for consideration. Before submitting the offer, the Company will provide advice and consultation regarding the information and terms of the reinsurance to the insurance company to ensure that the insurance company is prepared to enter into a reinsurance contract and to ensure that the insurance company's offer has terms that are most appropriate to the reinsurance needs.
2. Acceptance
After the reinsurer has received the offer, before sending a response or confirmation of reinsurance acceptance, the reinsurer will have a process of considering reinsurance from the offer and the information received. At this stage, the Company will act as an intermediary in negotiating with the reinsurer to obtain the best possible terms for the insurance company. After the reinsurer has considered the details to their satisfaction, the reinsurer will notify the Company of the consideration result or response. The Company will then prepare the acceptance document, which will specify the terms of the reinsurance contract and the proportion of reinsurance acceptance from the reinsurer, to be forwarded to the insurance company. Once the reinsurer has signed an agreement to accept reinsurance in the offer as mentioned in 1. above, the reinsurance contract is deemed to have been established because there is a correct and corresponding offer and acceptance.
3. Consideration
After a reinsurance contract has been established and each party has a contract with each other, the Company will act as an intermediary in collecting reinsurance premiums from the insurance company and forwarding them to the reinsurer according to the contract within the specified timeframe. At the same time, when there is a claim from the insurance company, the Company will act as a receiver of compensation from the reinsurer to forward to the insurance company according to the coverage of each insurance contract specified. After the insurance company and the reinsurer agree to enter into a reinsurance contract on mutually agreed terms, the Company will coordinate the preparation of reinsurance contract documents to complete the reinsurance contract process.
Nature of Business — Overview
Introduction
TQR Public Company Limited operates as a Reinsurance Broker, providing fully integrated reinsurance placement services as an Integrated Reinsurance Solution Provider. The Company's services encompass end-to-end advisory and placement services for cedant insurance companies, covering both Treaty Reinsurance and Facultative Reinsurance. In discharging its role, the Company evaluates the key components of reinsurance arrangements at the outset, including the reinsurance offer, class of business, terms and conditions of reinsurance, contractual agreements, and other relevant provisions, with the objective of securing the most optimal reinsurance terms for its business partners, both direct insurance companies and reinsurance companies. In addition, the Company collaborates in the analysis and development of reinsurance solutions, provides advisory services on innovative insurance products sourced from international markets and adapts them to align with the Thai insurance market, and coordinates between its business partners to facilitate efficient contract execution and the full achievement of their reinsurance objectives.
The Company currently operates as a non-life reinsurance broker and has earned the trust of both domestic and international business partners. Its business operations are categorized into 2 business segments, as follows:
1. Traditional Business
The Company acts as an intermediary between direct insurance companies and reinsurance companies, providing reinsurance placement services encompassing both Treaty Reinsurance and Facultative Reinsurance across all classes of business, including, amongst others, motor insurance reinsurance treaties, fire and property insurance reinsurance treaties, and miscellaneous insurance reinsurance treaties.
2. Alternative Business
The Company serves as an intermediary between direct insurance companies and reinsurance companies in the placement of both treaty and facultative reinsurance arrangements, in a manner consistent with the Traditional Business described above. Under the Alternative Business segment, however, the Company adopts a proactive business approach by actively seeking opportunities to participate in collaborative insurance product analysis and development with its business partners, providing advisory services on innovative insurance products sourced from international markets, and coordinating between its business partners to facilitate the efficient execution of reinsurance contracts.
Product Information — Overview
Introduction
Reinsurance is a form of risk management that is of critical importance to the insurance industry. Although a direct insurance company (cedant) may possess sufficient capital reserves and assets to meet its claims obligations under insurance policies issued to policyholders, should the cedant underwrite risks of a high-risk nature or of significant insured values, any loss event exceeding the cedant's actuarial projections may have a materially adverse impact on its capital adequacy and ongoing business operations. It is therefore imperative that direct insurance companies secure reinsurance arrangements to protect against losses arising from the underwriting of high-value risk exposures, and to maintain sound financial standing and sustainable operational performance.
The reinsurance process operates as follows: upon underwriting a risk, a direct insurance company retains a portion of that risk within its own capacity, known as the Retention, and transfers the remainder, whether in part or in full, to another party. The portion so transferred constitutes the Reinsurance.
In arranging reinsurance, regardless of the type of reinsurance treaty structure employed, a direct insurance company may elect to engage directly with a Reinsurer, or alternatively to transact through an intermediary known as a Reinsurance Broker, which may be either a Local Reinsurance Broker or an International Reinsurance Broker.
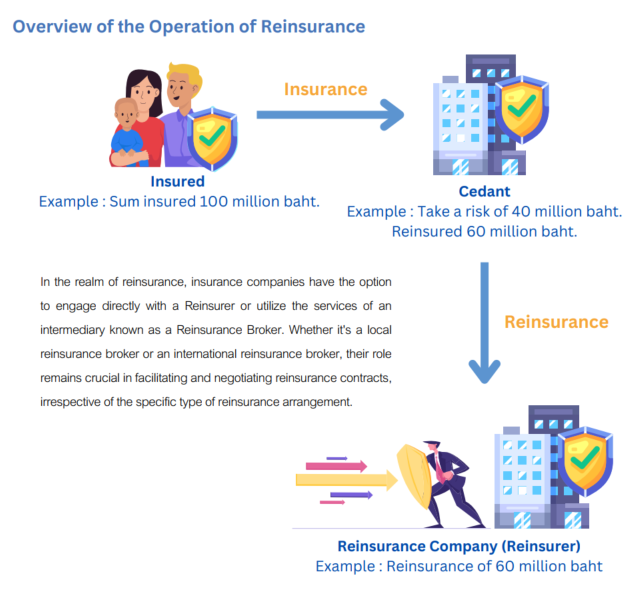
The Reinsurance Brokerage Business Supply Chain comprises the following participants:
Insured is a client who purchases insurance from a direct insurance company and agrees to pay a specified premium to the insurer. Upon the occurrence of a covered loss event, the direct insurance company is obligated to pay claims compensation to the insured.
Insurance Intermediary is acting as intermediaries in coordinating between the insured and direct insurance companies, categorized as follows:
2.1 Insurance Agent is an individual affiliated with a direct insurance company, acting on behalf of that company to solicit and present insurance products of the affiliated insurer to prospective policyholders.
2.2 Insurance Broker is an independent intermediary, which may be either a natural person or a juristic person, acting on behalf of prospective policyholders in selecting the insurance company whose policy best meets the client's needs. An insurance broker may recommend and sell insurance policies from any insurance company and operates independently, without affiliation to any particular insurer. Remuneration is received in the form of commission from the insurance company at rates prescribed by the Registrar for each class of insurance, which vary by product type. Under applicable law, a person may not simultaneously hold the status of both an insurance broker and an insurance agent; one role must be exclusively elected.
Cedant is the underwriter of various categories of risk, including fire, motor, marine and transportation insurance, amongst others. The cedant agrees to indemnify the insured for losses or damages incurred in accordance with the terms of the policy. In managing its underwriting risk, the cedant distributes risk through reinsurance arrangements to mitigate potential large-scale losses arising from any single loss event for which it bears liability. Such reinsurance may be arranged through either of the following channels:
Direct engagement between the cedant and the reinsurer, without the involvement of an intermediary; or
Engagement through an intermediary known as a Reinsurance Broker, to source appropriate reinsurance arrangements from various reinsurers.
Reinsurance Broker is an intermediary between direct insurance companies and reinsurance companies in the provision of reinsurance placement services, acting on behalf of both parties. The Reinsurance Broker's scope of services encompasses receiving reinsurance submissions from cedants, evaluating the components of the risk to be reinsured, coordinating the placement of appropriate reinsurance arrangements, and presenting terms to both direct insurance companies and reinsurance companies. The Reinsurance Broker receives remuneration in the form of a Reinsurance Brokerage Fee from the reinsurer.
Reinsurer is the entity that accepts reinsurance covering a broad range of risk categories, including property insurance, accident insurance, and others. Reinsurers may be either domestic reinsurance companies or international reinsurance companies.
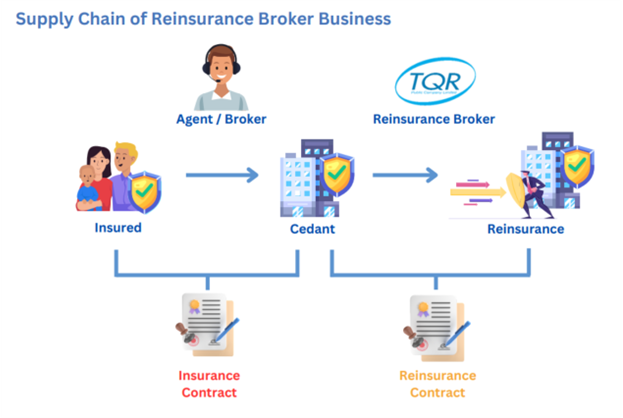
Reinsurance Contract
A reinsurance contract is an agreement whereby a reinsurer agrees to assume part or all of the risk exposure from a direct insurance company, in consideration for the receipt of a specified Reinsurance Premium, and undertakes to indemnify the direct insurance company upon the occurrence of a claim, in the amount and subject to the terms and conditions stipulated in the contract.
The Company's Key Role as a Reinsurance Broker
In Thailand, the reinsurance industry has long operated in parallel with the direct insurance industry. The critical importance of reinsurance was most vividly demonstrated during the catastrophic flooding of 2011, which inflicted severe damage on the Thai economy and had a profound direct impact on the domestic insurance industry, consequently, on the reinsurance industry as well. This event triggered a landmark transformation within the reinsurance sector.
In 2011, the Office of Insurance Commission ("OIC") introduced a policy to strengthen the resilience and capital adequacy of the insurance industry in response to rapidly evolving economic conditions and the changing risk environment. The OIC adopted the Risk-Based Capital ("RBC")1 framework for the insurance industry, and in 2019 further enforced the enhanced Risk-Based Capital 2 ("RBC 2")2 framework, to provide policyholders with greater assurance that insurance companies maintain sufficient financial strength to absorb potential risk exposures.
In 2023, the insurance industry was required to undergo a significant transition with the mandatory adoption of Thai Financial Reporting Standard No. 17 on Insurance Contracts ("TFRS 17")3, which introduced substantial changes to accounting practices and operational procedures for insurance companies, including revenue recognition, data collection processes, workflow management, and more stringent actuarial calculation requirements. These developments compelled insurance companies to recalibrate their business strategies and operational approaches to adapt to the changing landscape through rigorous risk management, including the strategic use of reinsurance which is anticipated to serve as a positive growth driver for the Company's financial performance going forward.
Furthermore, in 2025, two significant natural catastrophe events occurred: a magnitude 8.2 earthquake in Myanmar on 28 March 2025, which caused widespread damage across 18 provinces; and severe flooding in the southern region of Thailand in late November 2025, both of which inflicted substantial damage on the Thai economy and had a direct impact on the insurance and reinsurance industries. In particular, the earthquake fundamentally transformed the perception and assessment of seismic risk exposure in Thailand.
In light of the foregoing, the Company recognizes significantly enhanced business opportunities in the reinsurance brokerage sector, given that reinsurance constitutes a critical risk management mechanism enabling insurance companies to operate efficiently and maintain adequate capital reserves. The Company leverages its knowledge, capabilities, and deep expertise in reinsurance to assist in the analysis and assessment of domestic insurance risk exposures, with the aim of sourcing reinsurance arrangements that are optimally aligned with the business strategies of its partners, both direct insurance companies and reinsurance companies, while simultaneously generating added value to support the sustainable growth of its partners' businesses.
The Company's key roles in relation to its business partners, both direct insurance companies and reinsurance companies, are further elaborated as follows:
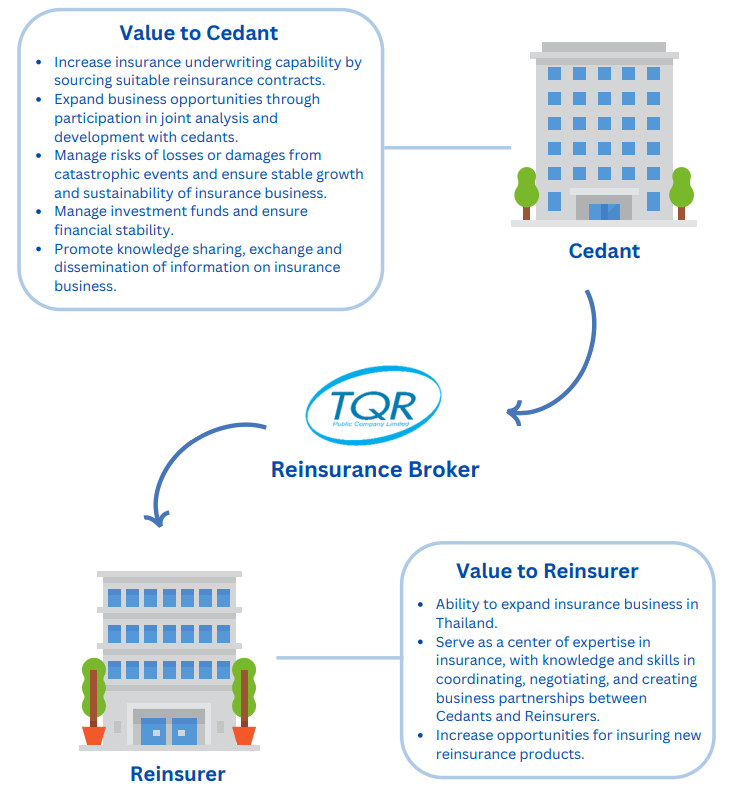
The Company's Key Roles in Relation to Direct Insurance Companies
1. Enhancing Underwriting Capacity through the Placement of Reinsurance Arrangements on Favourable Terms
The Company supports and expands opportunities for direct insurance companies to access international reinsurance markets. Through comprehensive research and comparative analysis, the Company identifies the most favourable terms and conditions on behalf of its cedant clients, enabling them to secure a diverse range of reinsurance structures and to effectively distribute risk among financially sound, capable, and specialist reinsurers. The Company further coordinates and assists in negotiations with reinsurers to secure the most competitive pricing and contractual terms, thereby enabling direct insurance companies to reduce their reinsurance placement costs.
2. Expanding Business Opportunities and Distribution Channels through New Insurance Product Development
The Company collaborates with direct insurance companies to promote the development of innovative insurance products in alignment with the evolving domestic insurance market. This is achieved by applying the Company's knowledge, expertise, and experience, or by adapting international insurance products to suit the specific business strategies of each direct insurance company in Thailand, with due consideration given to each cedant's risk appetite and the prevailing insurance business environment.
3. Managing Catastrophe Loss Exposure and Underwriting Volatility to Ensure Stability, Continuous Growth, and Sustainability
The risk exposure inherent in a direct insurance company's underwriting portfolio is directly correlated with the variability and uncertainty of the underlying risk events, which may materially affect projected claims costs and future cash flows. The Company fulfils its role by analyzing and monitoring domestic insurance market conditions, and providing the most appropriate and well-informed advisory recommendations to enable direct insurance companies to manage their underwriting risk with optimal effectiveness.
4. Capital Management and Financial Stability
Reinsurance serves as a key mechanism for risk distribution, enabling direct insurance companies to manage their capital reserves efficiently. By mitigating the risk of excessive capital erosion, reinsurance supports cedants in maintaining their capital at levels compliant with the requirements prescribed by the OIC and the Risk-Based Capital ("RBC") framework, thereby reinforcing the overall financial stability of direct insurance companies.
5. Knowledge Promotion, Information Exchange, and Industry Development
The Company organizes reinsurance training programmes for domestic insurance companies, with the objective of broadening and deepening awareness and understanding of reinsurance practices within the industry.
The Company's Key Roles in Relation to Reinsurance Companies
1. Supporting the Expansion of Reinsurance Business in Thailand
The Thai reinsurance market presents considerable growth potential relative to more developed markets, as evidenced by the continued increase in reinsurance premium volumes. This positions Thailand as a significant growth opportunity for reinsurers. However, certain international reinsurers may lack the necessary knowledge, understanding, and expertise in the specific risk characteristics relevant to reinsurance underwriting in Thailand. The Company is well-positioned to provide tailored advisory services on appropriate reinsurance underwriting strategies, supported by its dedicated Business Development Support Division, which is responsible for catastrophe risk assessment and modelling, appropriate risk management planning, and the identification and screening of the most suitable reinsurance opportunities for each respective reinsurer.
2. Acting as a Specialist Reinsurance Intermediary with Expertise in Coordination, Negotiation, and Business Partnership Development
Fundamentally, the Reinsurance Broker works in close collaboration with reinsurers by aggregating the requirements of both direct insurance companies and reinsurance companies, and coordinating the structuring of reinsurance contracts in accordance with mutually agreed terms and conditions. The Company provides comprehensive reinsurance support services, encompassing the planning and development of reinsurance structures on behalf of reinsurers, as well as the compilation of reinsurance submissions together with relevant premium and loss statistical data for presentation to reinsurers. Furthermore, in the event that a direct insurance company subsequently lodges a claim, the Company acts as intermediary in the negotiation process and facilitates the preliminary steps necessary to ensure the efficient and timely settlement of claims by the reinsurer.
3. Creating Expanded Reinsurance Opportunities in New Insurance Products
In recent years, the OIC has actively promoted the development of innovative insurance products to enhance market liquidity and strengthen the credibility and stability of the national insurance system. Concurrently, a range of emerging insurance products has gained increasing traction in the market, including Cyber Insurance, which has grown in demand in tandem with the rapid expansion of online data usage; Medical Malpractice Liability Insurance, which provides legal liability coverage for medical professionals; and Motor Add-on Insurance, a supplementary product offering coverage for medical expenses, daily hospitalisation income benefits, and transportation allowances during vehicle repairs following an accident. These developments represent significant opportunities for reinsurers to broaden their reinsurance underwriting portfolios. Given the Company's deep expertise in and thorough understanding of the domestic insurance market, it possesses comprehensive market intelligence to compare and present the most appropriate and competitive reinsurance terms to reinsurers.
Projects Under Construction
Has Projects Under Construction (Y/N)
No
Debentures & Bills of Exchange
Has Debentures (Y/N)
No
Convertible Securities
Has Convertible Securities (Y/N)
No