

MD&A · 2025
In this section4 topics
Overview of Operations
Overview of Operations
In 2025, the overall economic environment continued to face challenges arising from global economic volatility, inflationary pressures, geopolitical uncertainties, and rapid technological transformation. Nevertheless, these factors presented both positive and negative implications for the Company. The Company was able to effectively manage and adapt to such circumstances, resulting in continued overall business growth.
Heightened economic uncertainty and increasingly complex risks, particularly in relation to public health, natural catastrophes, climate change, and cyber threats, have led insurance companies to place greater emphasis on risk management and to increase their demand for reinsurance solutions. In particular, health insurance, critical illness insurance, and cyber insurance products have experienced stronger demand, serving as key drivers supporting the growth in the Company’s reinsurance brokerage volume and revenue.
Furthermore, the Company’s expertise and extensive experience in risk analysis and the provision of in-depth advisory services, together with its strong relationships with insurance companies (Cedants) and reinsurers (Reinsurers), both domestically and internationally, have enabled the Company to effectively develop new products and capitalize on emerging business opportunities. This has contributed positively to revenue growth and net profit expansion.
At the same time, economic volatility and intensified competition in the reinsurance brokerage industry, from both domestic and international players, have placed pressure on cost management, service quality maintenance, and the continuous development of human capital capabilities. The Company also faces regulatory risks arising from changes in laws, rules, and industry-related requirements.
The Company has realigned its operational strategies in response to prevailing conditions, with a focus on effective cost management, process optimization through the adoption of technology and digital systems, continuous upskilling of personnel, and strengthened risk management and good corporate governance practices, aiming to preserve competitiveness and ensure long-term financial stability.
As a result, in 2025, the Company recorded service income of THB 267.42 million, representing an increase of 7.87% compared to year 2024. The growth was primarily driven by higher revenue recognition across various reinsurance products, including Personal Accident and Health, Industrial All Risk, Political Violence, Professional Indemnity, Directors’ and Officers’ Liability (D&O), Cyber, and Crime reinsurance. Concurrently, the Company reported net profit of THB 100.53 million, an increase of 0.28%. The key contributing factors were the continued growth in service income from both Traditional Business and Alternative Business, with transaction volumes increasing consistently compared to the same period of the previous year.
Operating Results & Financial Condition
Operating Results & Profitability
Service Income
In the year 2024 and 2025, the Company had service income of THB 247.89 million and THB 267.42 million, respectively. In 2025, service income increased by THB 19.53 million or an increase of 7.88% from 2024 mainly from the increased in service income from Traditional Business and Alternative Business. The Company service income comes from providing brokerage services for reinsurance contracts divided into 3 segments according to the nature of the business:
For Traditional Business, in the year 2024 and 2025, the Company had service income of THB 74.56 million and THB 86.28 million, respectively. In 2025, Traditional Business service income increased by THB 11.72 million or 15.72% from last year. The increase mainly came from Property reinsurance from Fire and Industry all risk and Engineering reinsurance treaty business.
For Alternative Business, in the year 2024 and 2025, the services income was THB 172.17 million and THB 179.50 million, respectively. In 2025, Alternative Business service income increased by THB 7.33 million or 4.25% from last year. The increase derived from brokerage in Property reinsurance. Moreover, the Company has developed and focused on Specialty class such as Director’s & Officer’s Liability reinsurance, Political violence reinsurance, Cyber reinsurance, and Crime reinsurance.
Other Business is the revenue from subsidiary company which operates packaged software service provider and Seminar service. The Company recognized service contracts as revenue on a straight-line basis over the contract term.
Other income
Other income consists of interest income, dividend income, gain on fixed asset disposal and unrealized gain from securities investments.
For the year 2024 and 2025, the Company had other income of THB 11.02 million and THB 11.57 million, respectively. Other income increased by THB 0.55 million or 5.02% from last year. The reasons that increased came from gain on fixed asset disposal and unrealized gain from securities investment.
Cost of services
As the Company is a service business, the main cost of service is mainly human resources, who have expertise in Insurance and Reinsurance Business. Therefore, cost of service of the Company comprises of salaries, bonus, social security fund contribution and provident fund contribution for Client service.
For the year 2024 and 2025, the Company had cost of services of THB 59.59 million and THB 62.08 million, respectively. In 2025, cost of services increased by THB 2.49 million or 4.18 % from last year.
Gross Profit
For the year 2024 and 2025, the Company had gross profit of THB 188.31 million and THB 205.34 million, respectively. In 2025, gross profit increased by THB 17.03 million of 9.04% from last year. The increase was mainly from the increase in services income from Brokerage re-insurance.
Selling Expenses
Selling expenses is mainly from selling expenses to expand channel in Alternative Business. For the year 2024 and 2025, the Company had selling expenses of THB 5.63 million and THB 5.64 million, respectively.
Administrative Expenses
For the year 2024 and 2025, the administrative expenses of the Company were THB 70.00 million and THB 80.14 million, respectively. The administrative expenses increased by THB 10.13 million or 14.47%, mainly increased from personnel expenditure and headcount, along with expenses for organizing the 14-year Moving Forward event to drive the organization towards sustainability and increases from maintenance costs and increased amortization from information technology assets in use.
Other expenses
For the year 2024 and 2025, the Company had other expenses THB 0.45 million and THB 7.00 million, respectively. The other expense increased by THB 6.55 million or 1446.46%, mainly from from unrealized foreign exchange losses and losses on investments in securities measured at fair value, that decreased depend on Fair Market value. However, in 2025, the Company had unrealized gain from securities investment from Fair value as other income.
Share of profit of associates
The Company has invested in Alphasec Co., Ltd., in portion 30% as associated company. For the year 2024 and 2025, the Company have taken equity THB 2.97 million and THB 2.53 million, respectively.
Income tax expenses
For the year 2024 and 2025, the Company had income tax expenses of THB 25.44 million and THB 25.57 million, respectively. The increase of THB 0.14 million was in proportion to the increase in Company profit.
Net Profit
For the year 2024 and 2025, the Company net profit was THB 100.25 million (38.72% of sales) and THB 100.53 million (36.03% of sales), respectively. The increase in net profit of THB 0.29 million or 0.28 % from last year, resulted from the Company having service income for nine-month increasing from Traditional Business and Alternative Business. However, the administrative expenses and other expenses increased in the same way.
Liquidity & Capital Adequacy
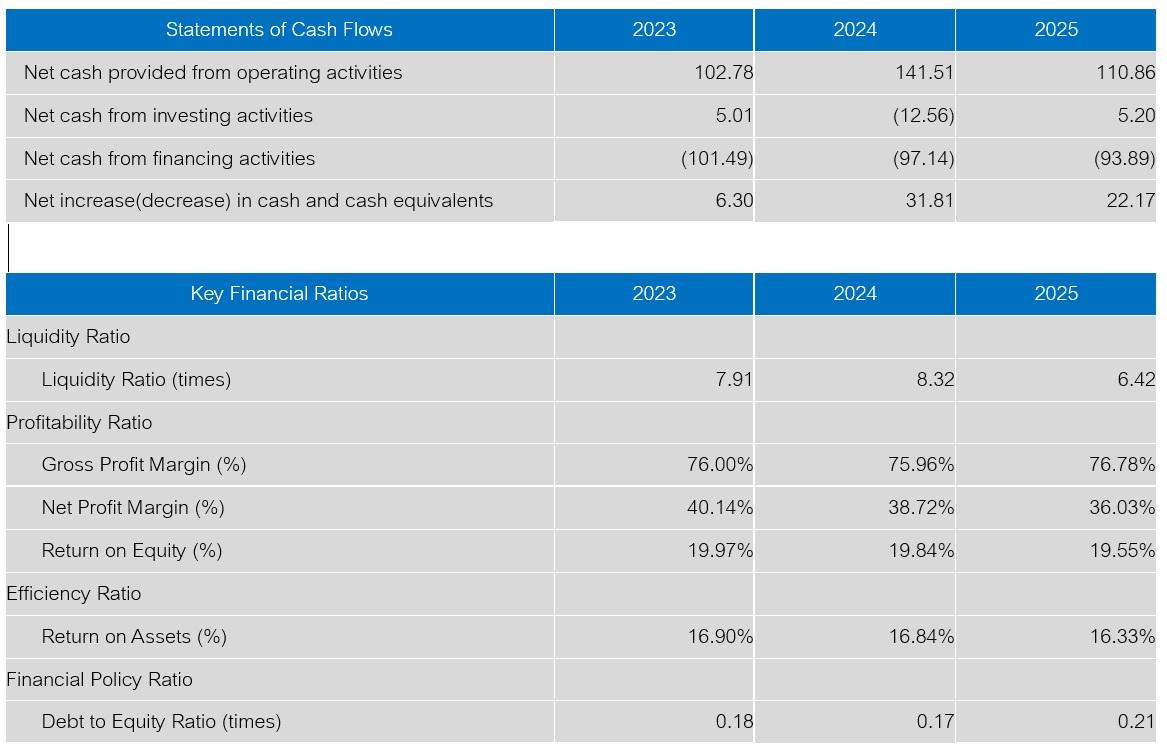
Asset Management Capability
Assets
As of 31 December 2024 and 2025, the Company’s total assets amounted to THB 599.05 million and THB 632.30 million, respectively, representing an increase of THB 33.25 million, or 5.55%. The increase was primarily attributable to higher cash and cash equivalents, as well as accrued service income and other current receivables.
Liabilities
As of 31 December 2024 and 2025, the Company’s total liabilities amounted to THB 86.39 million and THB 109.01 million, respectively, representing an increase of THB 22.62 million, or 26.19%. The increase was mainly due to higher reinsurance premium payables and other current payables.
Equity
As of 31 December 2024 and 2025, the Company’s total shareholders’ equity amounted to THB 512.66 million and THB 523.28 million, respectively, representing an increase of THB 10.63 million, or 2.07%. The increase was primarily attributable to higher retained earnings resulting from the Company’s net profit generated during the year, thereby strengthening shareholders’ equity.
Debt Securities with Financial Ratio Requirements
Debt Securities with Financial Ratio Requirements Issued?
No
Factors That May Affect Financial Condition
Factors or Incidents That May Materially Affect Financial Condition
The Company anticipates that the transition toward an aging society, rising health awareness, and increasing prevalence of critical illnesses may continue to drive demand for health and critical illness insurance. While these trends present growth opportunities, they may also heighten underwriting risks and lead to volatility in claim costs if actual health risk patterns deviate from the assumptions used in pricing. In parallel, rapid technological advancement and escalating cybersecurity threats could influence both the growing demand for cyber insurance and the Company's own operational risk exposure, potentially affecting reputation, customer trust, and the cost of cybersecurity investments. Moreover, climate change and the increasing frequency and severity of natural disasters may significantly elevate the risk of insurance and reinsurance claim losses, particularly if the Company is unable to manage or diversify such risks effectively through appropriate risk-transfer mechanisms. Additionally, increasing stakeholder expectations regarding corporate governance, transparency, and responsible business practices under the ESG framework may impact the Company's competitiveness, access to capital, and long-term investor confidence if timely adaptation to emerging standards and regulatory requirements is not achieved. In response, the Company is strengthening its readiness by integrating technology and innovation into product development, expanding strategic collaborations in insurance and reinsurance and enhancing enterprise risk management systems to mitigate potential impacts on its financial position and operating performance.